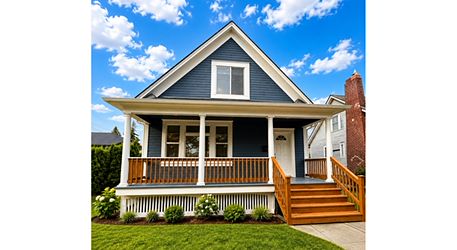
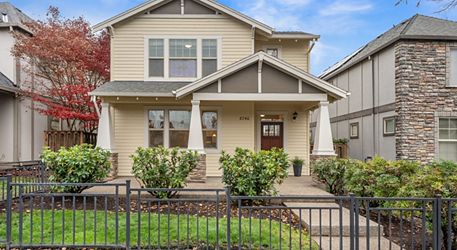
First-Time Home Buyer Guide to Portland, Oregon
Practical help with budgeting, local assistance programs, and a clear path from pre‑approval to closing your first Portland home.
Welcome to your first home‑buying adventure in Portland, Oregon.
Think about a sustainable monthly budget that feels comfortable for your household, covering not only the mortgage payment but also utilities, insurance, and a cushion for unexpected repairs.
Focus on financing early: review your credit score, explore pre‑approval options, and learn about Oregon‑specific assistance programs that can lower upfront costs.
Our guide walks you step‑by‑step through budgeting, financing basics, neighborhood research, home inspections, and the closing process, giving you the local knowledge you need to move forward with confidence.
Budget Beyond the Price: What Can You Comfortably Afford?
Expense
When paid
How to estimate or verify
Down payment
Upfront at closing
Calculate using the agreed purchase price and your loan program’s down payment requirement. Confirm any assistance arrangements with your lender.
Closing costs and prepaid items
Upfront at closing
Review your lender’s Loan Estimate and Closing Disclosure for lender fees, appraisal charges, title insurance, escrow fees, prepaid homeowners insurance and property tax escrow deposits.
Mortgage principal and interest
Monthly
Use your lender’s quoted interest rate, loan amount and loan term to calculate the payment. Keep this amount separate from taxes, insurance and other ownership expenses.
Property taxes
Annually; often collected monthly through mortgage escrow
Review the specific parcel’s official tax statement and assessment history through the Multnomah County Division of Assessment, Recording, and Taxation. Oregon uses the lower of Real Market Value or Maximum Assessed Value to determine assessed value; the property’s Levy Code Area also affects the bill. Do not estimate taxes by multiplying the purchase price by a general tax rate.
Homeowners insurance
Initial premium upfront at closing; subsequently through monthly escrow or annual payments
Obtain insurance quotes for the specific property address. Replacement cost, construction type and property risks affect the premium.
HOA dues, where applicable
Monthly or quarterly
Verify current dues in the property’s homeowners association disclosure packet, listing documents or management company statement.
Utilities
Monthly
Request the seller’s historical bills or address-specific usage information from utility providers. Include water, sewer, stormwater, electricity and natural gas where applicable.
Repairs and maintenance reserves
Ongoing; repairs paid as needed
Use the professional home inspection findings and the condition of the roof, sewer line, heating and cooling equipment, and plumbing to plan a reserve for maintenance and repairs.
Set your own payment ceiling before shopping. Start with your household’s take-home pay, then subtract debt payments, childcare, groceries, transportation, other recurring obligations and planned savings. Use what remains to set a comfortable limit for total housing costs—not just mortgage principal and interest. Include property taxes, insurance, any HOA dues, utilities and a repair reserve when comparing Portland homes.
Lender qualification is not the same as comfortable affordability. Treat the amount a lender approves as a borrowing limit, not a spending target. Your personal ceiling should leave room for everyday life and unexpected expenses. Keep emergency savings separate from the money earmarked for your down payment, closing costs and prepaid items; a purchase that drains that cushion deserves another look.
Compare Loan Estimates side by side. Request estimates using comparable loan amounts, loan terms and down payments so differences are easier to understand. Review the interest rate, principal-and-interest payment, lender fees, prepaid items, escrow amounts and total cash needed at closing. Ask the lender to explain differences rather than choosing solely by the advertised rate or monthly payment. Check property taxes against the home’s actual records and insurance against an address-specific quote before deciding whether the full cost fits your budget.
Find Portland and Oregon homebuyer support
Resource
What it offers
Eligibility and access
Next action
Portland Housing Bureau Down Payment Assistance Loan Program
A second mortgage used alongside a first mortgage from a participating lender.
The property must be within Portland city limits. Income and first-time homebuyer requirements apply. Access is through approved community partners, not a direct application to the city; assistance depends on available funding.
Review current project availability through the Portland Housing Bureau Programs Portal and connect with an approved community partner or certified housing counselor.
Oregon Housing and Community Services FirstHome
A fixed-rate first mortgage for eligible low- to moderate-income first-time homebuyers, with down payment assistance that can also help cover closing costs and prepaid items.
Available statewide, including Portland, through approved participating lenders. County purchase price limits, household income caps, credit requirements and underwriting apply. Assistance may be a forgivable or repayable second mortgage; eligibility is not guaranteed.
Use the Oregon Housing and Community Services FirstHome Lenders Portal to review participating lenders and verify applicable limits and assistance terms.
Arrive, formerly Portland Housing Center
Housing counseling, personalized Action Plans, HomeBuying 101 classes, Financial Fitness workshops and access to down payment assistance programs.
Serves prospective and current homeowners in the Portland metropolitan region. Education fulfills certification requirements for local and state financing programs; assistance access remains subject to program requirements.
Register for an initial orientation or information session through Arrive, formerly Portland Housing Center.
Get Mortgage-Ready: Credit, Lenders and Preapproval
Prepare recent pay stubs, W-2 forms, bank statements, investment or retirement account statements, and a government-issued photo ID. Include documentation of gift funds you plan to use.
List recurring debts with creditor details, balances and minimum monthly payments. Ask your lender which tax returns and additional income records it needs, especially if you are self-employed or receive bonuses or overtime.
Prequalification is a preliminary borrowing estimate based on financial information you report. It is not the same as a lender reviewing your documents.
Preapproval involves a hard credit check and verification of income, debts and assets. In Portland, a preapproval letter can strengthen your offer. Ask what conditions remain and when the letter needs updating before you rely on it.
Ask your lender to review your credit history alongside your income, monthly debt obligations and funds available for the purchase. Eligibility depends on the loan program and your overall finances, not a universal credit-score cutoff.
Request a side-by-side explanation of conventional loans and any government-backed options you may qualify for. Have the lender explain how down payment requirements, mortgage insurance, property standards and documentation differ before choosing a loan.
Request Loan Estimates from different lenders using matching loan amounts and terms. Compare the interest rate, estimated monthly payment, origination charges, points, lender credits and total cash needed to close—not just the advertised rate.
Evaluate costs over the time you realistically expect to keep the loan. Ask lenders to explain trade-offs between upfront charges and ongoing payments rather than assuming a future refinance will make the loan affordable.
Ask about the Portland Housing Bureau’s Down Payment Assistance Loan Program and assistance through Oregon Housing and Community Services before submitting an offer. Confirm eligibility, participating-lender requirements, homebuyer education and funding availability with the program.
Coordinate with your lender and real estate agent so the offer reflects any assistance-related approval, inspection or closing requirements. Do not assume assistance funds are secured until the program confirms your approval and funding arrangements.
Compare Portland homes with daily life in mind
Test real‑world commutes – before you decide on a neighborhood, drive the typical route to work, school or the places you shop during peak traffic. Include any bridge crossings and use the local transit schedule to see how long a bus or light‑rail ride will take at rush hour. Seeing the experience yourself, rather than relying on online estimates, reveals hidden delays.
Visit properties at multiple times – a home that feels quiet in the morning may be noisy when the kids return from school or when evening traffic peaks. Walk around the block at lunch, after dinner and on a weekend to gauge noise, foot traffic and overall ambience. These observations help you picture daily life in the space.
Compare home types and HOA rules – condos, townhouses and single‑family homes each carry different maintenance responsibilities. Request the homeowners’ association’s governing documents, budget and recent meeting minutes. Understanding fees, reserve funds and any restrictions (such as pet policies or exterior changes) prevents surprises later.
Assess ongoing maintenance and energy costs – ask the seller for recent utility bills, HVAC service records and roof age. An older furnace or aging roof can add to monthly expenses. If the home has a smart thermostat or upgraded insulation, those features may lower energy use. Factor these operating costs into your overall budget, not just the purchase price.
Check permit records – request copies of building permits for any remodels, additions or electrical work. The City of Portland’s permit database confirms that work was inspected and approved, protecting you from unpermitted upgrades that could affect resale value or safety. Verified permits give confidence that the home meets code.
Professional inspection versus appraisal – a licensed home inspector examines the structure, systems and potential safety issues such as roof leaks, plumbing defects or foundation movement. The inspector’s report helps you negotiate repairs or price adjustments. An appraiser, on the other hand, determines the current market value based on comparable sales; they do not provide a detailed condition assessment. Both reports serve different but essential roles in the buying process.
Specialized tests when relevant – if the property is older, consider a sewer scope to verify the condition of underground pipes. In areas where radon is a known concern, a radon test measures indoor air quality and may indicate the need for mitigation. For homes that previously used oil heating, an oil‑tank evaluation ensures the tank is intact and compliant with local regulations. These targeted inspections focus on risks that are not always visible in a standard walk‑through.
Typical inspection cost example – a comprehensive home inspection often runs around $350, providing a detailed snapshot of the home’s condition before you finalize your offer. Budgeting for this expense early helps keep the overall purchase timeline on track.
Your first-home buying roadmap in Portland
Take your next step toward homeownership
Choose a monthly housing budget you can sustain, then gather your income and savings documents, including tax returns, pay stubs and bank statements.
Contact an official homebuyer educator or participating lender to discuss education and assistance eligibility. The Portland Housing Bureau’s Buying a Home resource is a place to start.
Common First-Time Buyer Questions
Not necessarily. Low-down-payment mortgages and assistance programs may reduce the cash you need, depending on your eligibility. Ask your lender to compare the down payment, closing costs and full monthly payment for each option. Assistance may be a loan rather than a grant, so review repayment terms before committing.
Possibly. Many programs consider you a first-time buyer if you have not owned a residential property in the past 3 years. Some offer exceptions for purchases in designated targeted areas. Confirm the specific program’s ownership rules and other eligibility requirements before assuming you qualify.
Base your decision on an affordable monthly payment, your timeline and your household’s financial stability—not an expected rate drop. Compare loan options available to you now, including the Oregon Bond Residential Loan Program’s Rate Advantage option if eligible. Avoid relying on future refinancing to make a purchase affordable.
No. The Portland Housing Bureau’s Down Payment Assistance Loan requires the home to be within Portland city limits. Other programs have their own geographic, income and purchase-price requirements, and assistance depends on available funding. Confirm the property’s eligibility with the program before relying on assistance.
Yes—student loans do not automatically disqualify you. Lenders evaluate that debt alongside your income and other obligations. A deferred loan may still count in the calculation, so ask your lender how your student loans affect mortgage qualification and any assistance program you plan to use.
Nov 13, 2026
Read More